The stories behind financial success
Before the deposit: Kunal Sharma on the gap between eligibility and a funded home loan
For Mortigo founder Kunal Sharma, one costly misunderstanding in a Dubai property purchase comes early: treating an initial indication of eligibility as if it were a loan ready to fund a particular home.
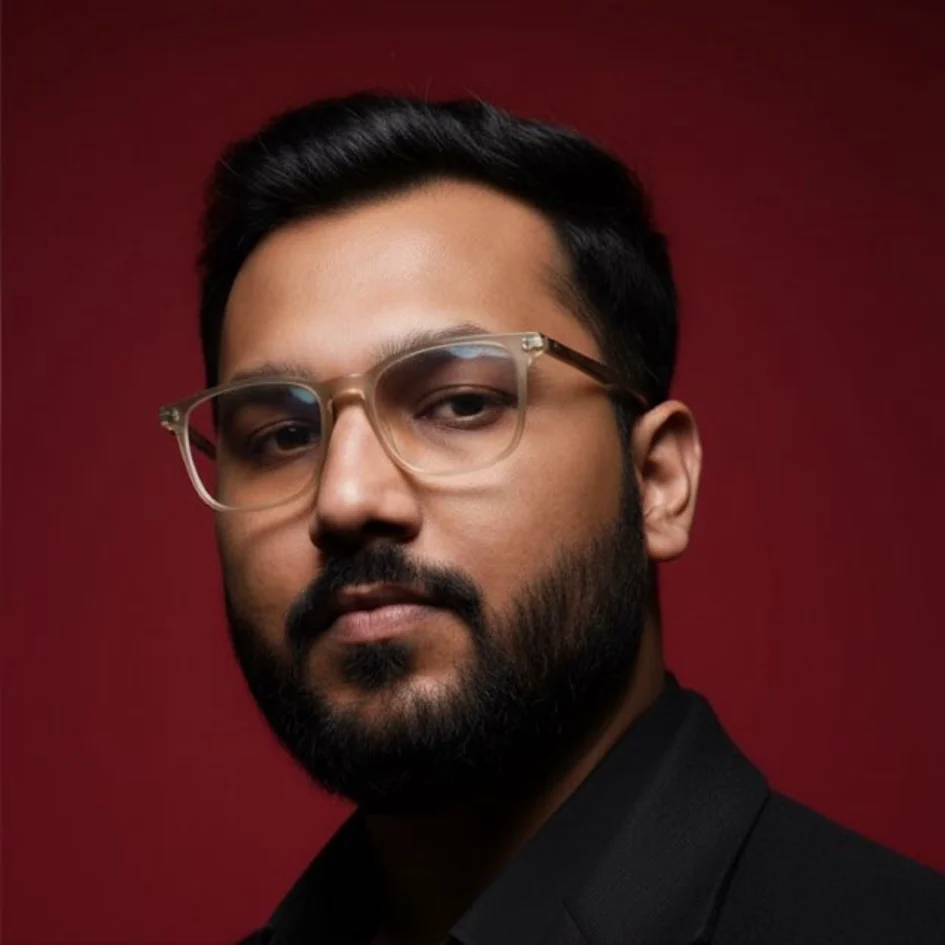
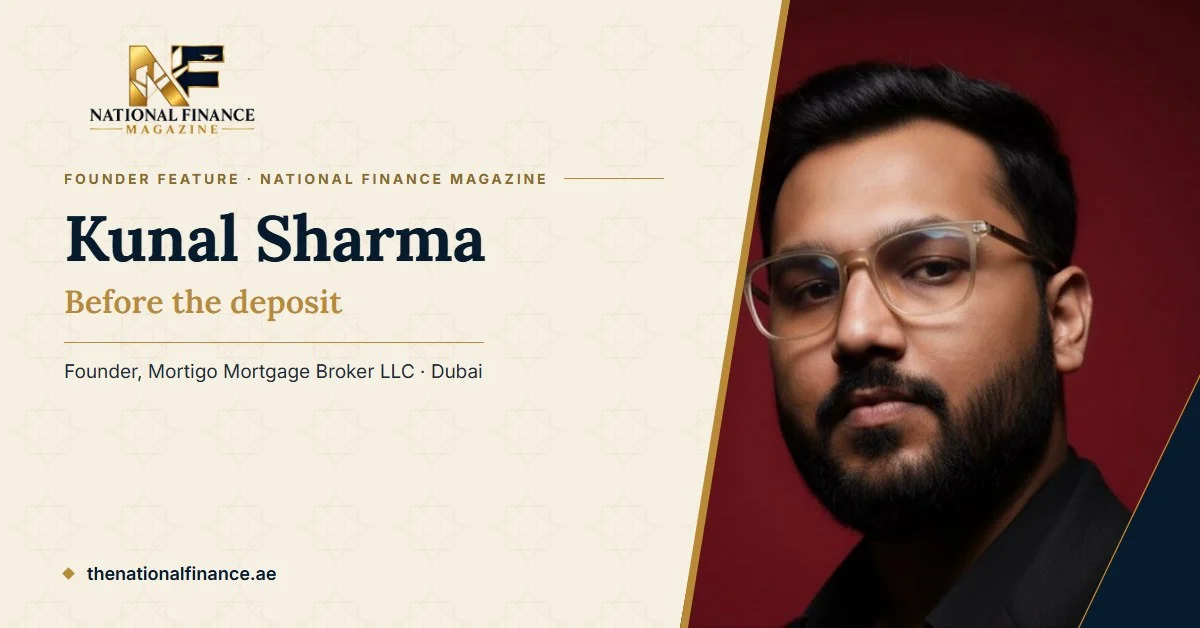
For Dubai mortgage broker Kunal Sharma, one of the most costly misunderstandings in a property purchase happens early: treating an initial indication of eligibility as if it were a loan ready to fund a particular home.
Sharma founded Mortigo Mortgage Broker LLC after more than four years in the UAE mortgage market. In his account, the work that matters most sits between a buyer’s first enquiry and the moment a purchase is funded, when separate checks on the borrower, the property and the cash required finally come together.
Eligibility is not a commitment
Sharma describes a persistent tension in his industry between speed and certainty. Borrowers understandably want an immediate answer, but a preliminary assessment of income does not commit a lender to finance a specific unit.
A lender’s assessment of income and liabilities, its acceptance of the particular unit or project, an independent valuation and the cash needed at completion are, in his description, distinct decisions. He says the distinction matters most for first-time, overseas and off-plan buyers, who may commit to a deposit before every condition has been tested.
“A preliminary assessment of income is not a commitment to finance a particular unit.”
Kunal Sharma, interview with National Finance Magazine
An illustration in numbers
To show how a gap can open, Sharma offers a purely hypothetical case rather than a client example. For an illustrative eligible first-home buyer purchasing a completed property, an assumed 80% loan-to-value ratio on an AED 2 million purchase would mean expected funding of AED 1.6 million. If the lender’s accepted valuation is AED 1.9 million, the same ratio produces an illustrative maximum of AED 1.52 million, leaving the buyer to find another AED 80,000 in cash before transaction costs.
Actual eligibility and lender policy vary, he notes. His point concerns timing: conditions and funding risks should be explained before someone commits to a purchase, not after.
Advice beyond the headline rate
Mortigo works with UAE residents and non-resident buyers on mortgage options for property purchases, refinancing and buyouts, equity release and handover financing. Sharma says the firm concentrates on helping clients understand the documentation, affordability, lender policies and property-specific conditions behind a proposed loan.
He names building Mortigo as a licensed brokerage, with advice that looks beyond an advertised interest rate, as his proudest achievement. A useful mortgage conversation, in his view, should leave a buyer knowing what has actually been assessed, what remains conditional and how much cash they may still need.
Better data, the same checks
Sharma expects UAE mortgages to become more data-assisted. Better document handling and credit information can improve early assessments, he says, but they do not remove a lender’s checks on income, liabilities, the property and final disbursement. Buyers, he argues, should be able to see exactly what an automated estimate does and does not establish.
For the regulatory background, he points readers to the Central Bank of the UAE’s mortgage regulation and Dubai Land Department’s mortgage-registration services.
What comes next
Mortigo’s priorities, Sharma says, are stronger buyer education, more consistent document and underwriting workflows, and better lender matching, so that clients can make informed decisions from initial enquiry through to completion.
His advice to young professionals follows the same line. Build trust through explanations people can follow and consistent follow-through. Learn the underlying rules before relying on a calculator. And be willing to say that a financing outcome is still conditional.
The Founder’s Lesson
- Treat an indication of eligibility and a commitment to fund a specific property as separate decisions.
- Understand the valuation and the cash needed at completion before paying a deposit.
- Ask what an automated estimate does and does not establish.
Editorial takeaways drawn from Kunal Sharma’s interview answers.
About Kunal Sharma
Kunal Sharma is the founder of Mortigo Mortgage Broker LLC, a mortgage brokerage based in Dubai, United Arab Emirates (mortigo.ae).
By the National Finance Magazine Editorial Team. Based on Kunal Sharma’s written answers to National Finance Magazine’s interview questions (31 October 2026) and correspondence with the magazine. The funding figures are a hypothetical illustration supplied by the interviewee, not a client case. This article is general information, not financial or mortgage advice.
More from the magazine
More stories beyond success
National Finance Magazine
Every business has a story behind it.
Explore the decisions, discipline and people shaping business.